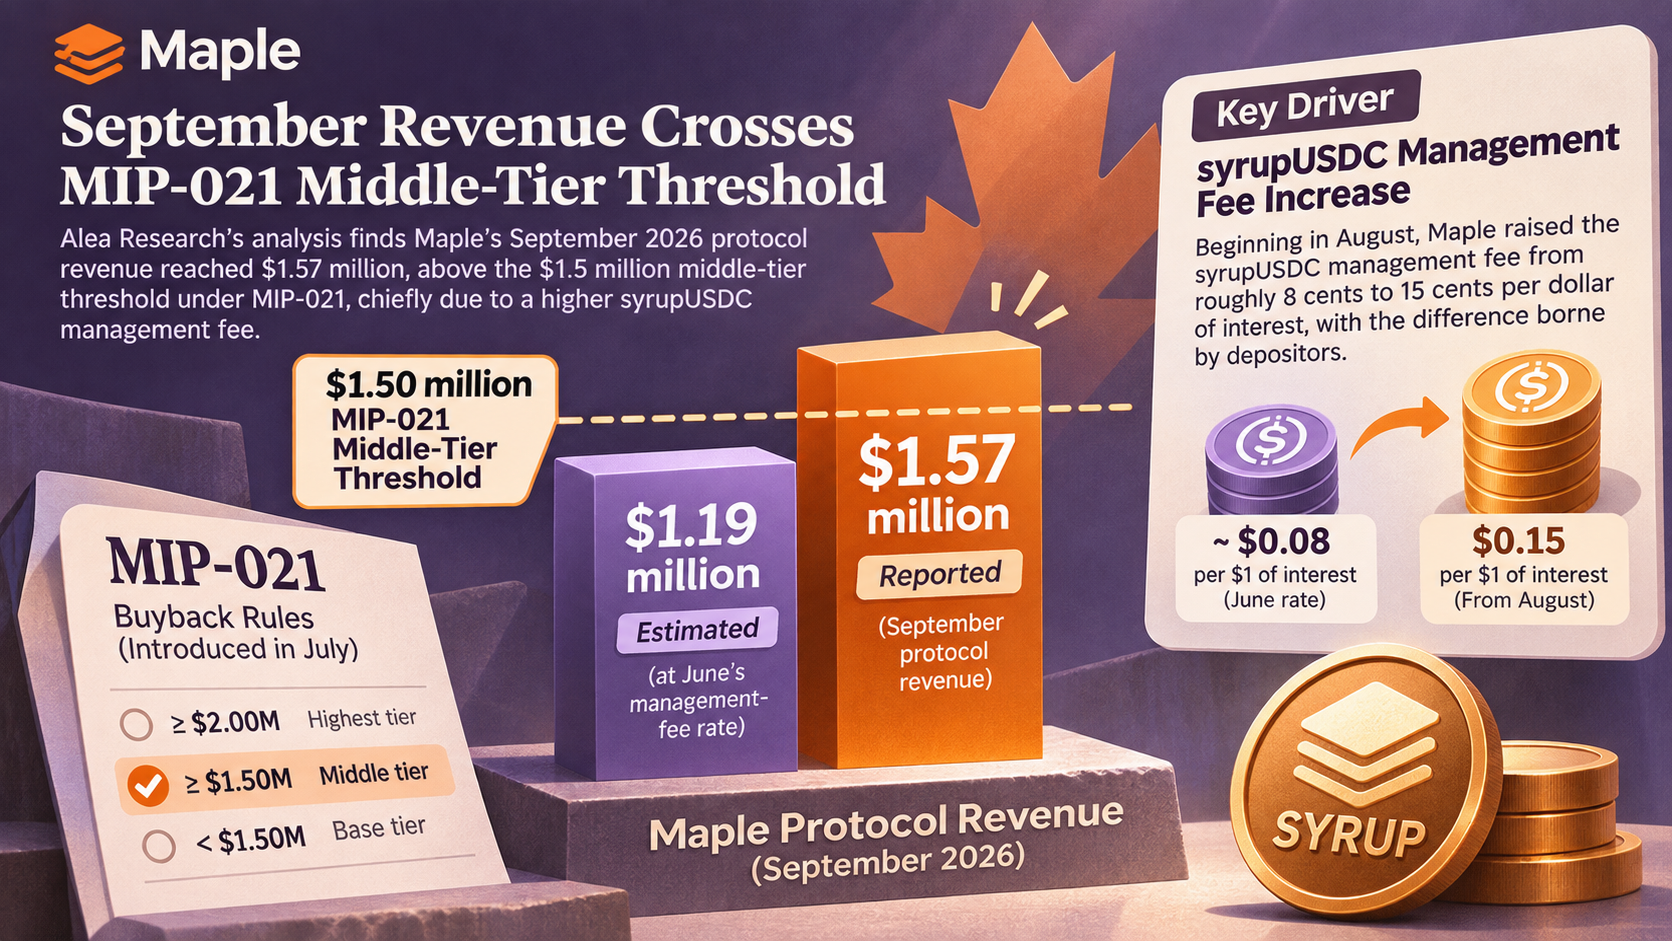
Reported November 13, 2026, at 09:37 (UTC+8). In an analysis by Alea Research translated by Deep Tide TechFlow, Maple’s September protocol revenue reached $1.57 million. That put the month above the $1.5 million threshold for the middle buyback tier under MIP-021, the rules introduced in July. The analysis attributes the result chiefly to a higher syrupUSDC management fee, rather than deposit growth.
Fee change and buyback status
Beginning in August, as loans entered their next interest-payment periods, Maple raised the syrupUSDC management fee from roughly 8 cents to 15 cents per dollar of interest. Depositors bore the difference. Alea Research estimates that, at June’s fee rate, September revenue would have been about $1.19 million—below the middle-tier threshold.
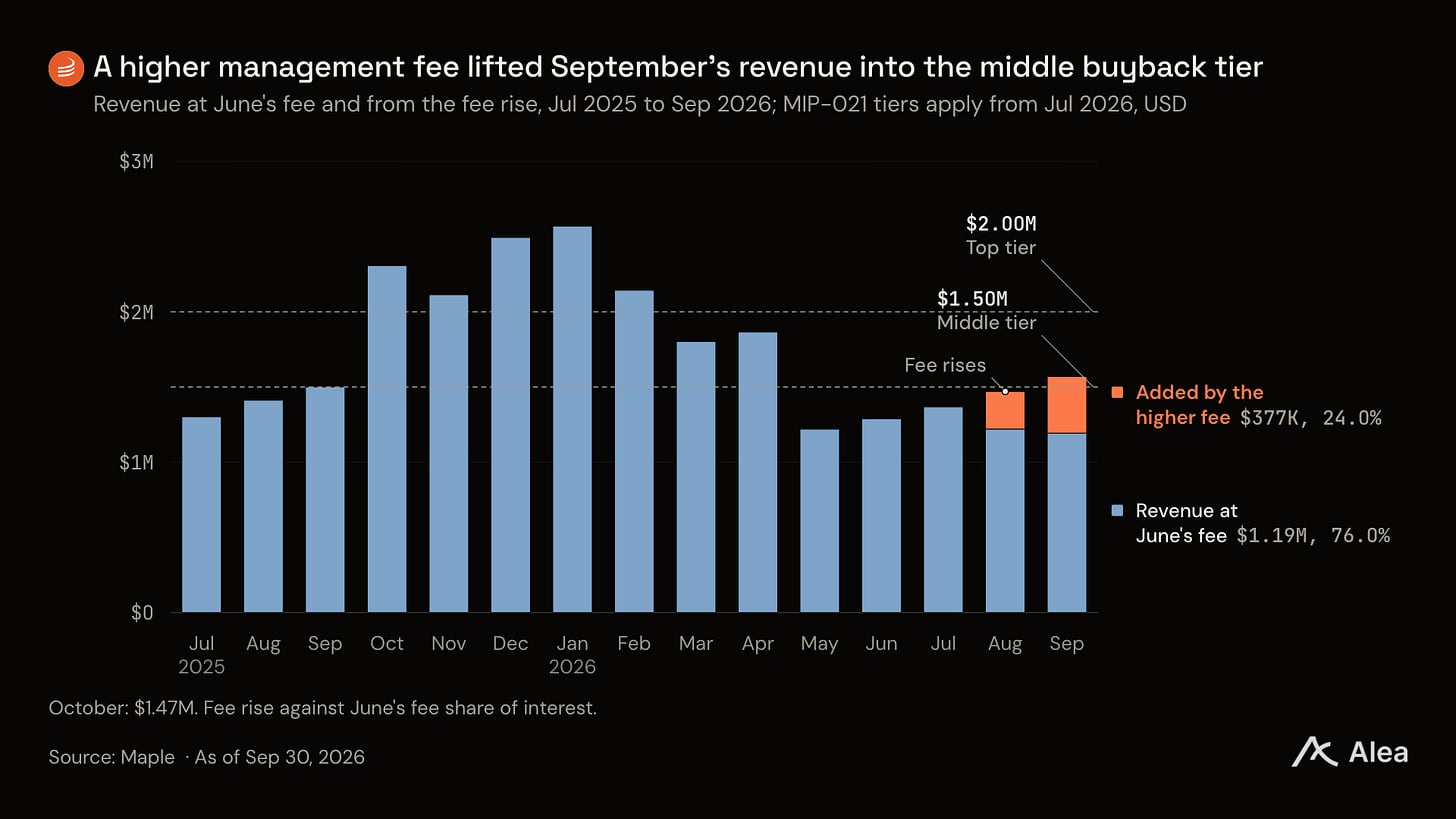
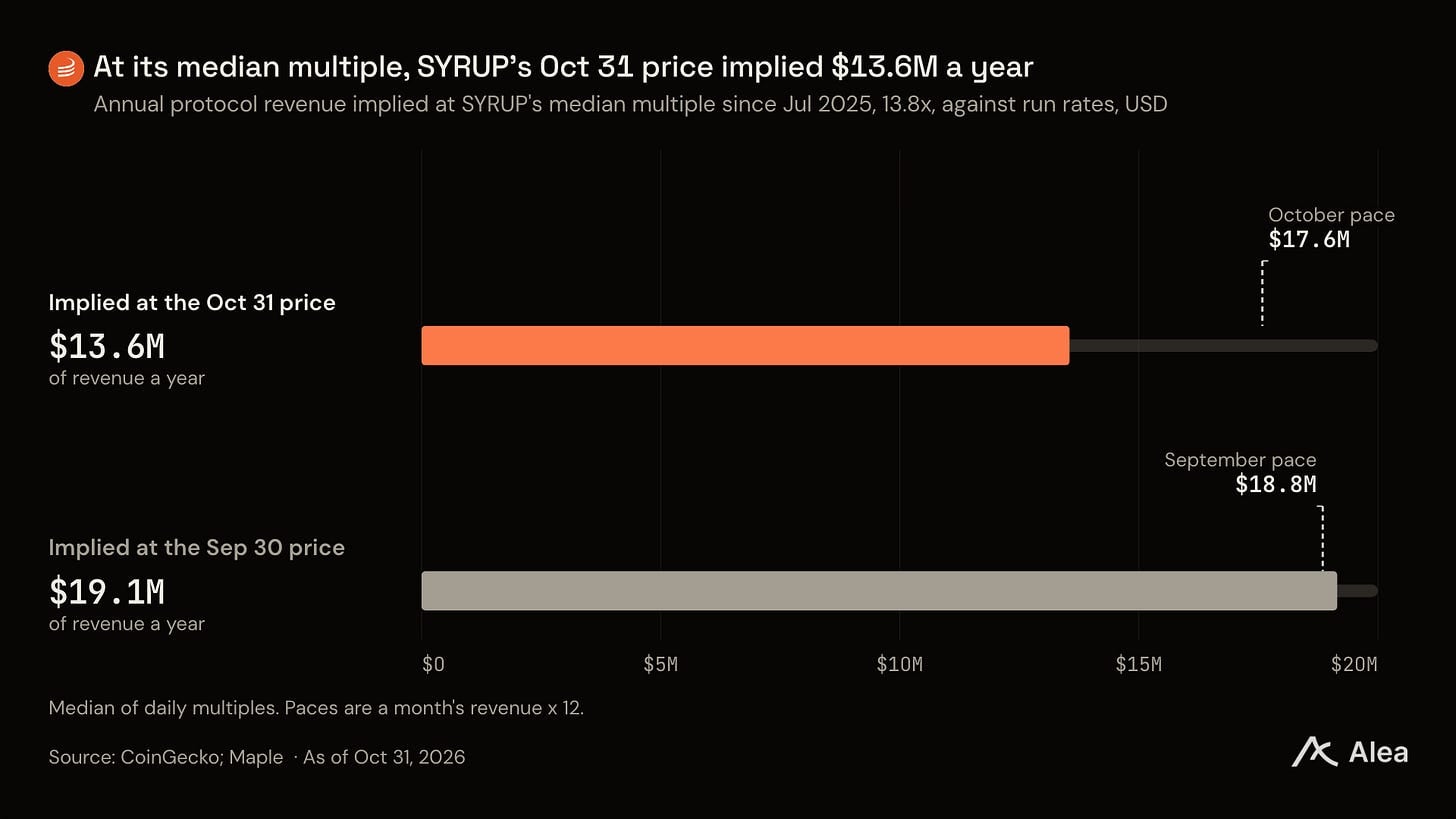
Third-quarter revenue totaled $4.41 million, compared with $4.38 million in the second quarter. Under MIP-021, buyback funding amounted to 13.6% of third-quarter revenue, and 2.9 million SYRUP was purchased for the Syrup Strategic Fund. October revenue then fell to $1.47 million, returning that month’s buyback share to 10%, or approximately $147,000. The source says October was about $35,000 short of the middle-tier threshold.
Deposits shifted across channels
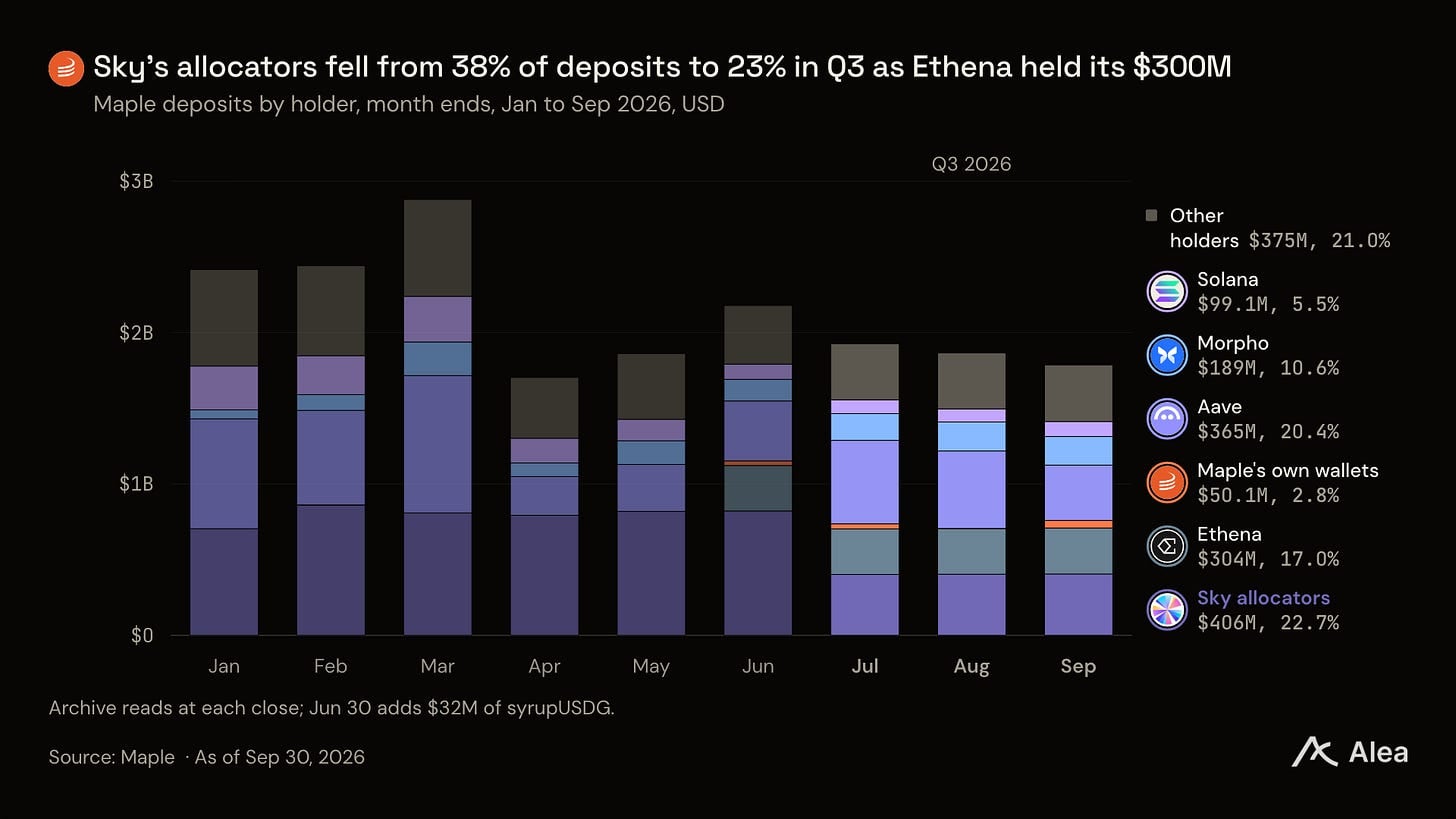
Maple’s total deposits fell 17% during the third quarter as two Sky allocators redeemed funds and leveraged syrupUSDT positions left Plasma. The Sky allocators’ holdings declined from $822 million on June 30 to $406 million on September 30. Over the same quarter, syrupUSDG, launched July 1, attracted $176 million in deposits. Alea Research also reports growth in Aave’s Monad market for syrupUSDC and its Ethereum market for syrupUSDT.
Withdrawal timing later changed. For syrupUSDC requests submitted October 31, the median wait was 44 hours, versus approximately three minutes from July 1 through October 27. The analysis reports further pauses in queue payouts before requests returned to settlement within minutes from November 10.
What remained conditional
Alea Research estimates that reaching MIP-021’s highest buyback tier would require $2.31 billion in deposits at September’s revenue per dollar of deposits, or $2.6 billion at October’s rate. These are scenario estimates, not scheduled buybacks. As of the source’s November 13 publication, November revenue—and whether it would return buybacks to the middle tier—had not been established.
Source: techflowpost.com (originally published 2026-11-13 09:37 UTC+8)